


Central Asia Takes Off: Investments in Civil Aviation Infrastructure (Updated)
13 October 2026
The analytical brief has been updated to reflect the latest data on Kyrgyzstan's airports and includes an assessment of actual investment in their infrastructure, as well as a forward-looking assessment based on open data and international experience of investment in airports.
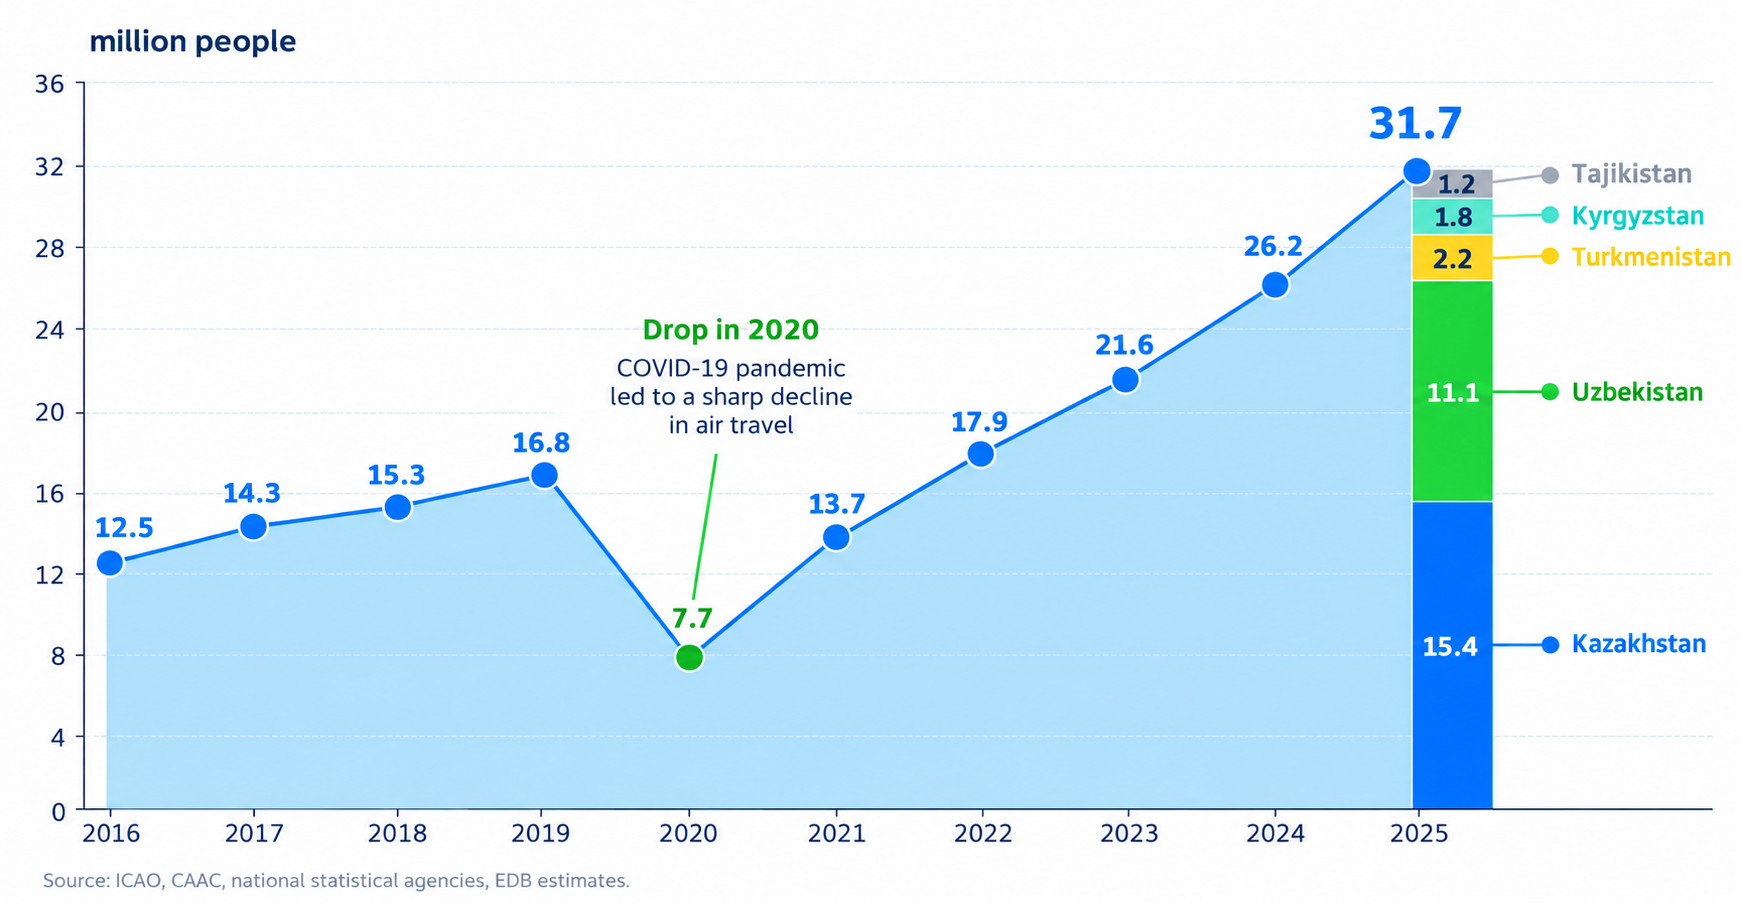
Air transport in Central Asia is growing rapidly. In 2025, airlines in the region’s five countries carried 31.7 million passengers, nearly double the pre-pandemic level.
SUMMARY
-
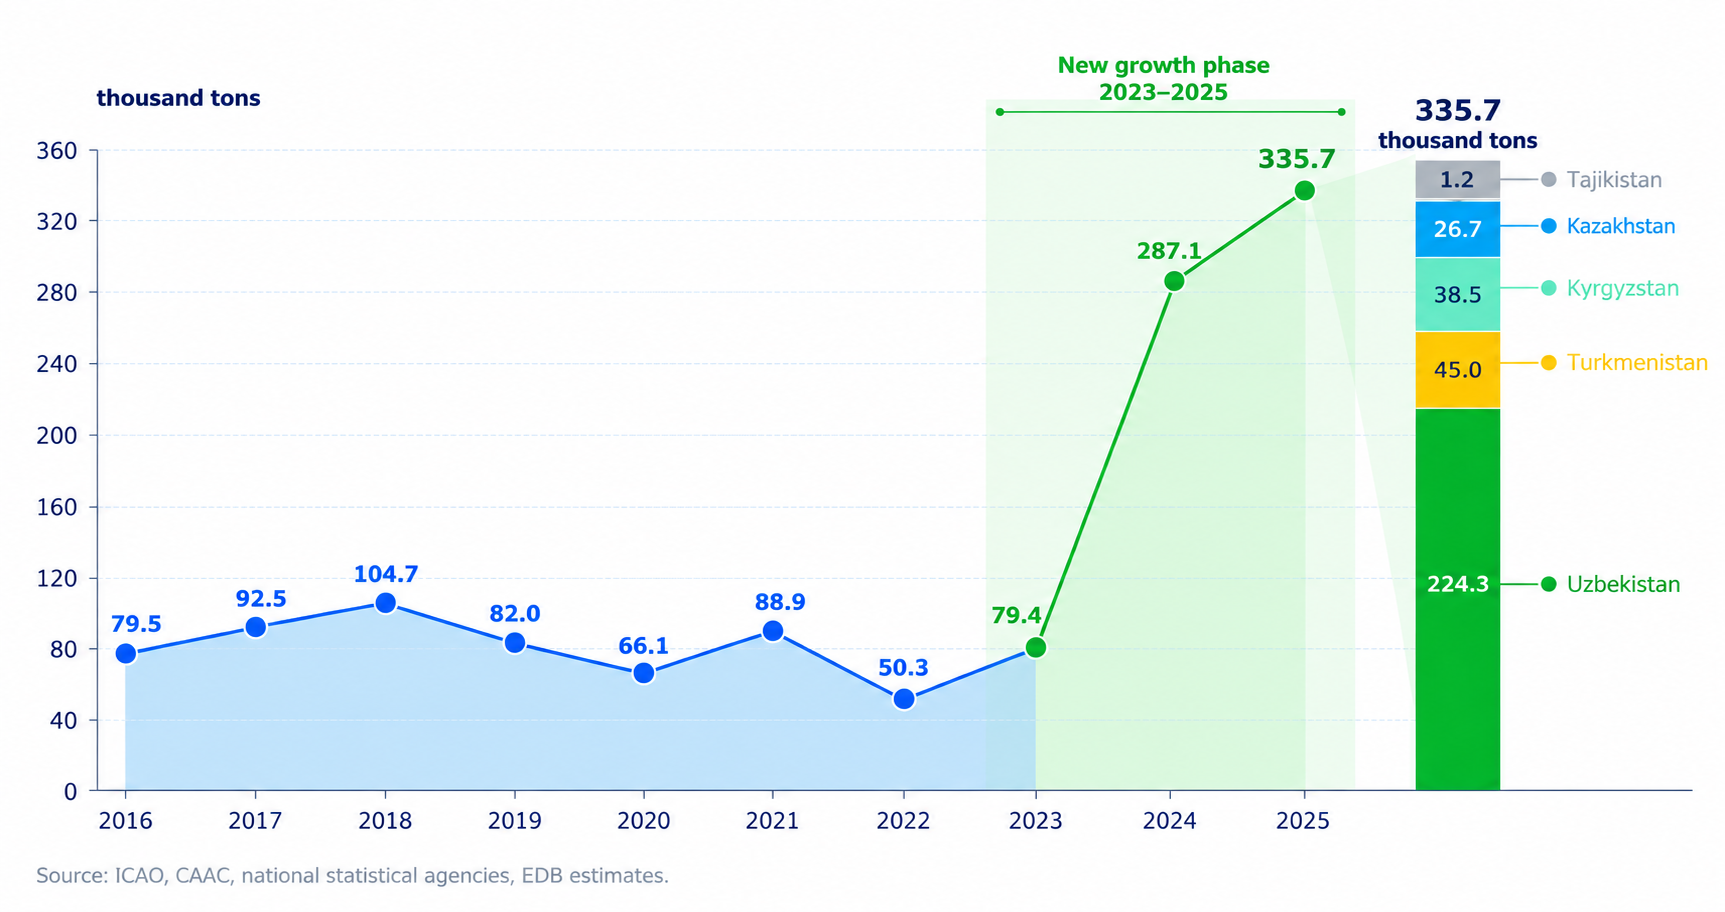
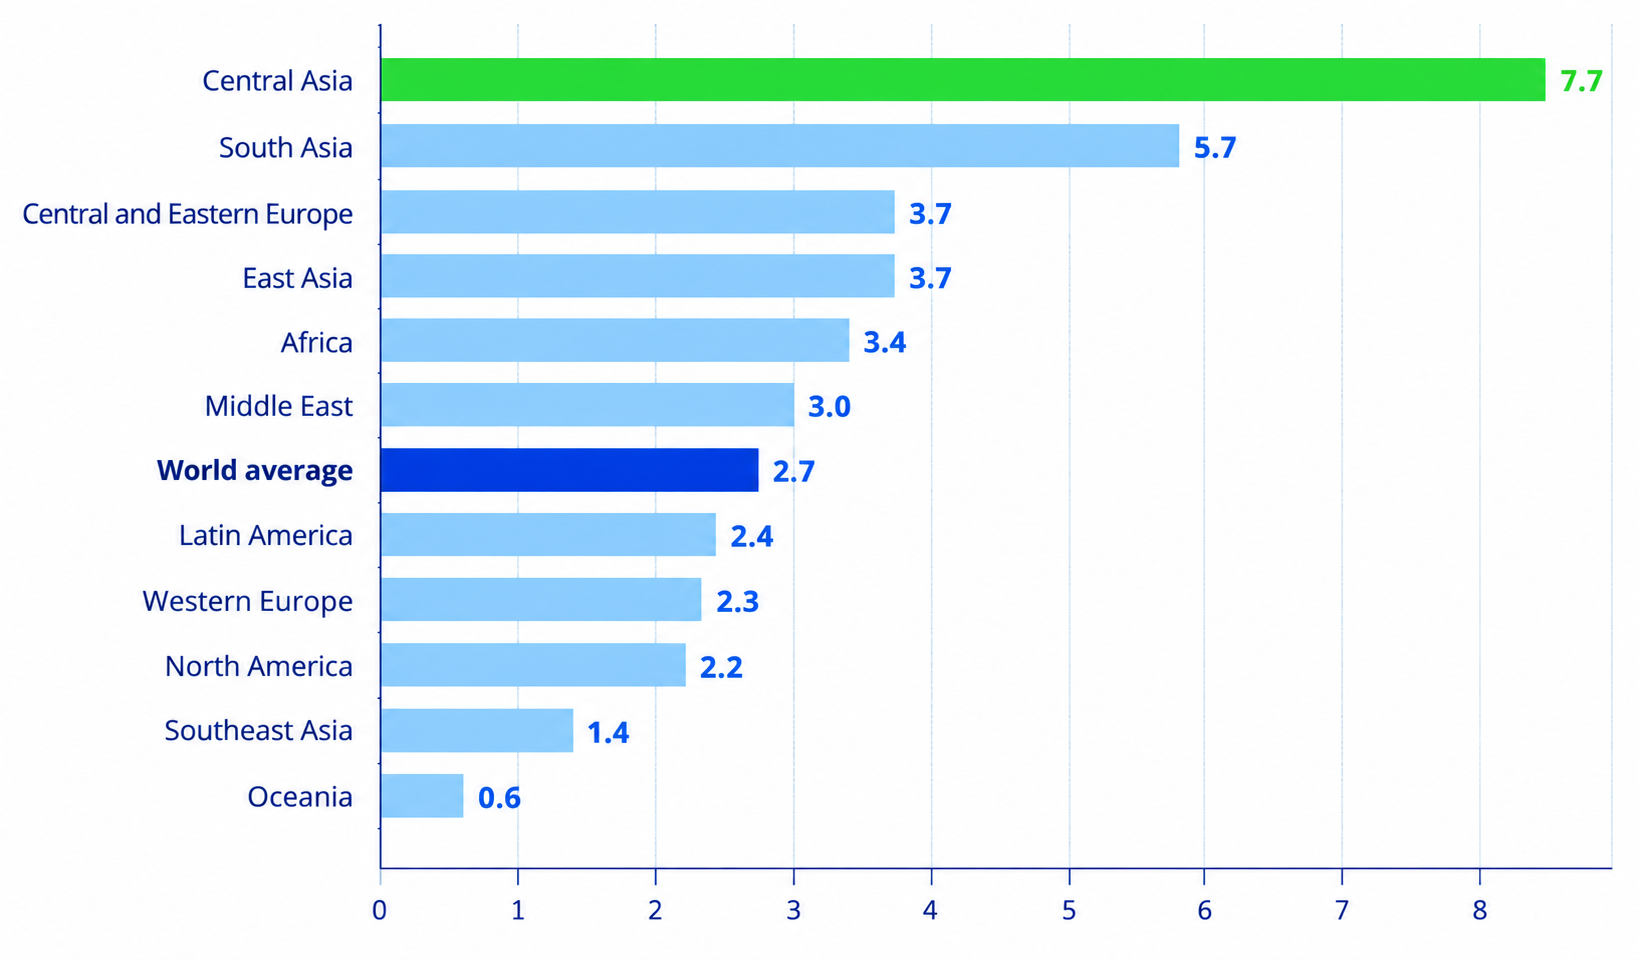
Air transport in Central Asia 1 is growing rapidly. In 2025, airlines in the region’s five countries carried 31.7 million passengers, nearly double the pre-pandemic level. From 2015 to 2025, the available capacity of the aircraft fleet grew by an average of 7.7% per year, nearly three times faster than the global market. The volume of air cargo traffic for 2023–2025 more than quadrupled, reaching 335,700 metric tons.
-
Infrastructure is expanding. Foreign direct investment stock in the region’s air transport sector totals $1.4 billion. By 2035, 12 major airport development projects worth $5.1 billion will be implemented or planned.
-
Investment opportunities span the entire industry. Demand is growing for warehouses, new aircraft, and aircraft maintenance and refueling services. Additional potential lies in low-cost carriers, intra-regional air service, and cargo transit.
-
Further growth requires regulatory modernization. Priorities include expanding “open sky” policy, especially for cargo; improving market access conditions for airlines, including low-cost carriers; developing regional alliances; and advancing digitalization. Dialogue among the aviation authorities of the region’s countries, the business community, ICAO, IATA, and other international organizations, multilateral development banks, and the expert community will help coordinate solutions.
Rapid development of the Central Asian air transport market
The main factors are the sustained economic growth of the region’s five countries (GDP growth by a factor of 13, from $46 billion to $567 billion between 2000 and 2025), an increase in population (from 55 to 83 million people) and per capita disposable income, as well as greater population mobility.
- Compared to the pre-pandemic peak (2019), the number of passengers carried nearly doubled, reaching 31.7 million in 2025.
- Kazakhstan has the largest passenger air travel market and an extensive airport network (Fig. 1). In 2025, it accounted for 48.7% of all passenger air travel in Central Asia, while Uzbekistan accounted for 35%, Turkmenistan for 7%, Kyrgyzstan for 5.6%, and Tajikistan for 3.7%.
- The passenger air travel market in Uzbekistan grew the fastest - tripling compared to its pre-pandemic peak (2019) and reaching 11.1 million passengers.
The air cargo market is growing even faster:
- The volume of air cargo transported on scheduled and non-scheduled flights, both international and domestic, has more than quadrupled since 2023, reaching 335,700 metric tons in 2025 (Fig. 2).
- This is only slightly less than the volume of air cargo transportation in Russia (446,700 metric tons in 2025). In 2019, the volume of air cargo transportation in Russia was 14 times greater than in Central Asia (1,147.2 thousand versus 82 thousand metric tons).
- By 2025, Uzbek airlines had strengthened their position in the air cargo market in Central Asia. Uzbekistan accounted for about 67% of all air cargo transported by the national airlines of the five countries. The rapid growth in recent years has been driven by the emergence of new cargo airlines, the expansion of their aircraft fleets, the development of cargo transit between third countries, the increase in e-commerce volumes, and changes in flight routes across the Eurasian region, primarily through Russia.
Figure 1. Number of passengers carried by airlines of Central Asian countries, millions
Sources: ICAO, Interstate Aviation Committee (IAC), national statistical agencies, EDB analysts’ calculations
Figure 2. Volume of cargo transported by airlines registered in Central Asian countries, in thousands of metric tons
Sources: ICAO, IAC, national statistical agencies, EDB analysts’ calculations
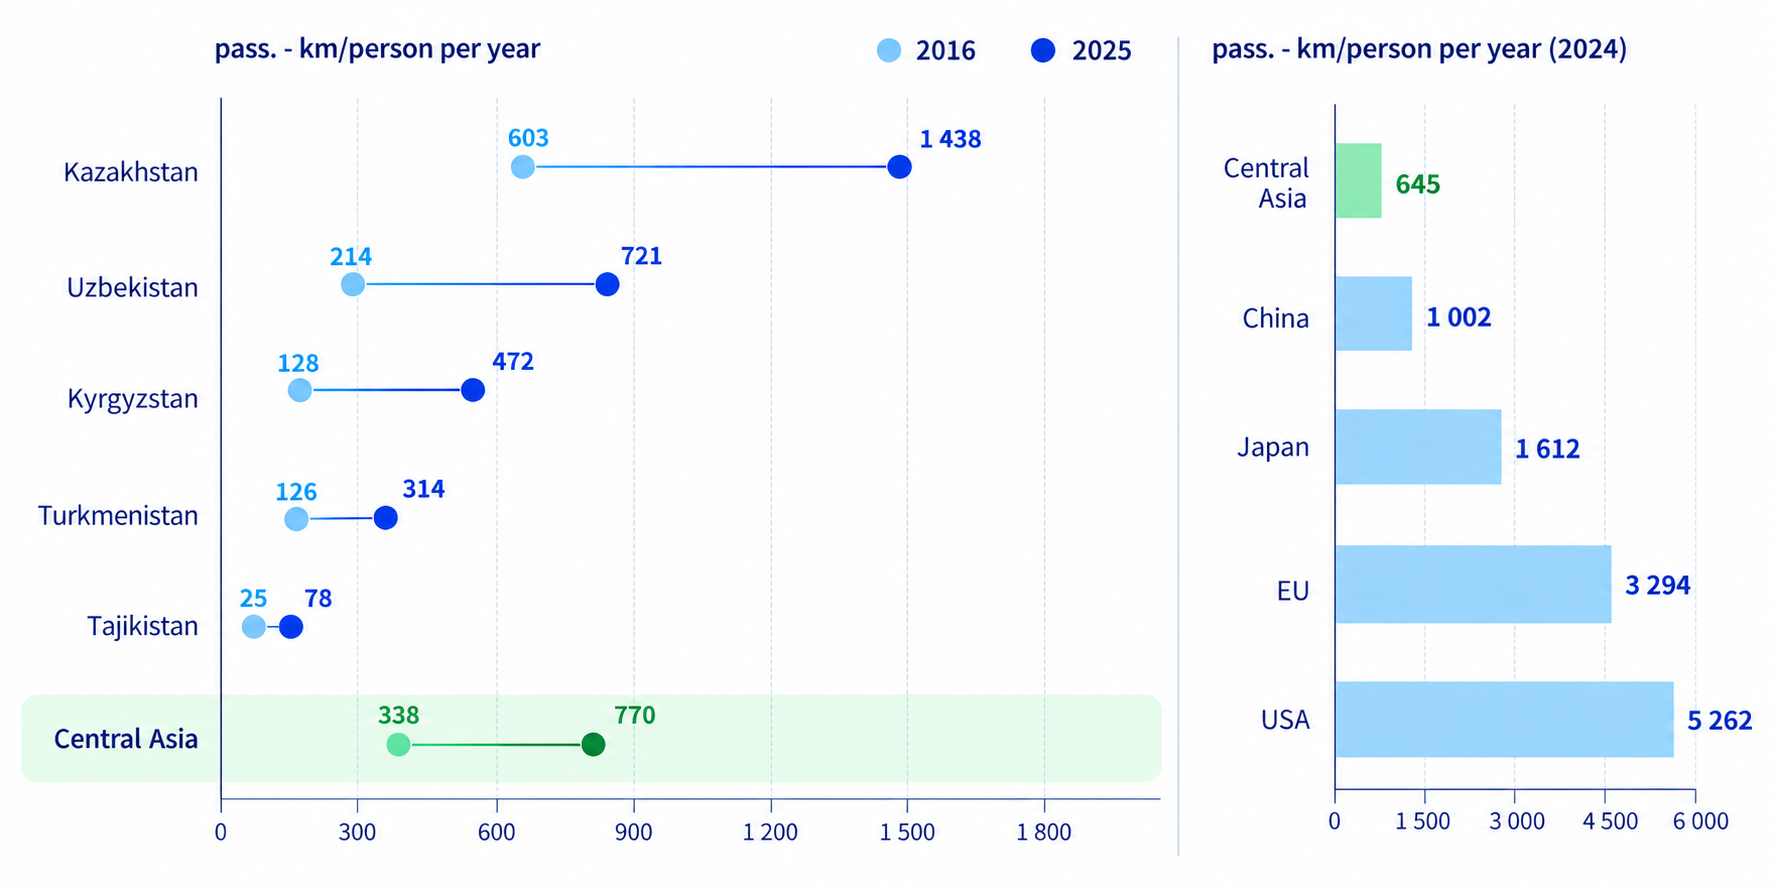
The growth in air mobility among the people of Central Asia is one of the main drivers of growth in the passenger air transport market. People have begun to fly more. Over the past 10 years, the number of passenger-kilometers per capita in Kazakhstan has increased 2.4-fold. In Uzbekistan, the growth was even more significant—a 3.4-fold increase (Fig. 3). At the same time, air mobility among the population in Central Asia has significant potential for growth, as evidenced by the prior experience of China and other developed air transport markets.
Figure 3. Air mobility in Central Asian countries, passenger-km per capita per year
Sources: ICAO, Eurostat, World Bank, IAC, national statistical agencies, EDB analysts’ estimates.
The market’s growth is evidenced by the large-scale aircraft fleet renewal and expansion programs being implemented by airlines in Central Asian countries. The compound annual growth rate (CAGR) of available passenger seat capacity in the region was 7.7% for the period 2015–2025, the highest rate among all regions of the world. Carrying capacity in Central Asia grew three times faster than the global average (Fig. 4).
Figure 4. Compound Annual Growth Rate (CAGR) of Available Passenger Seat Capacity for the period 2015–2025, %
Source: Official Aviation Guide (OAG).
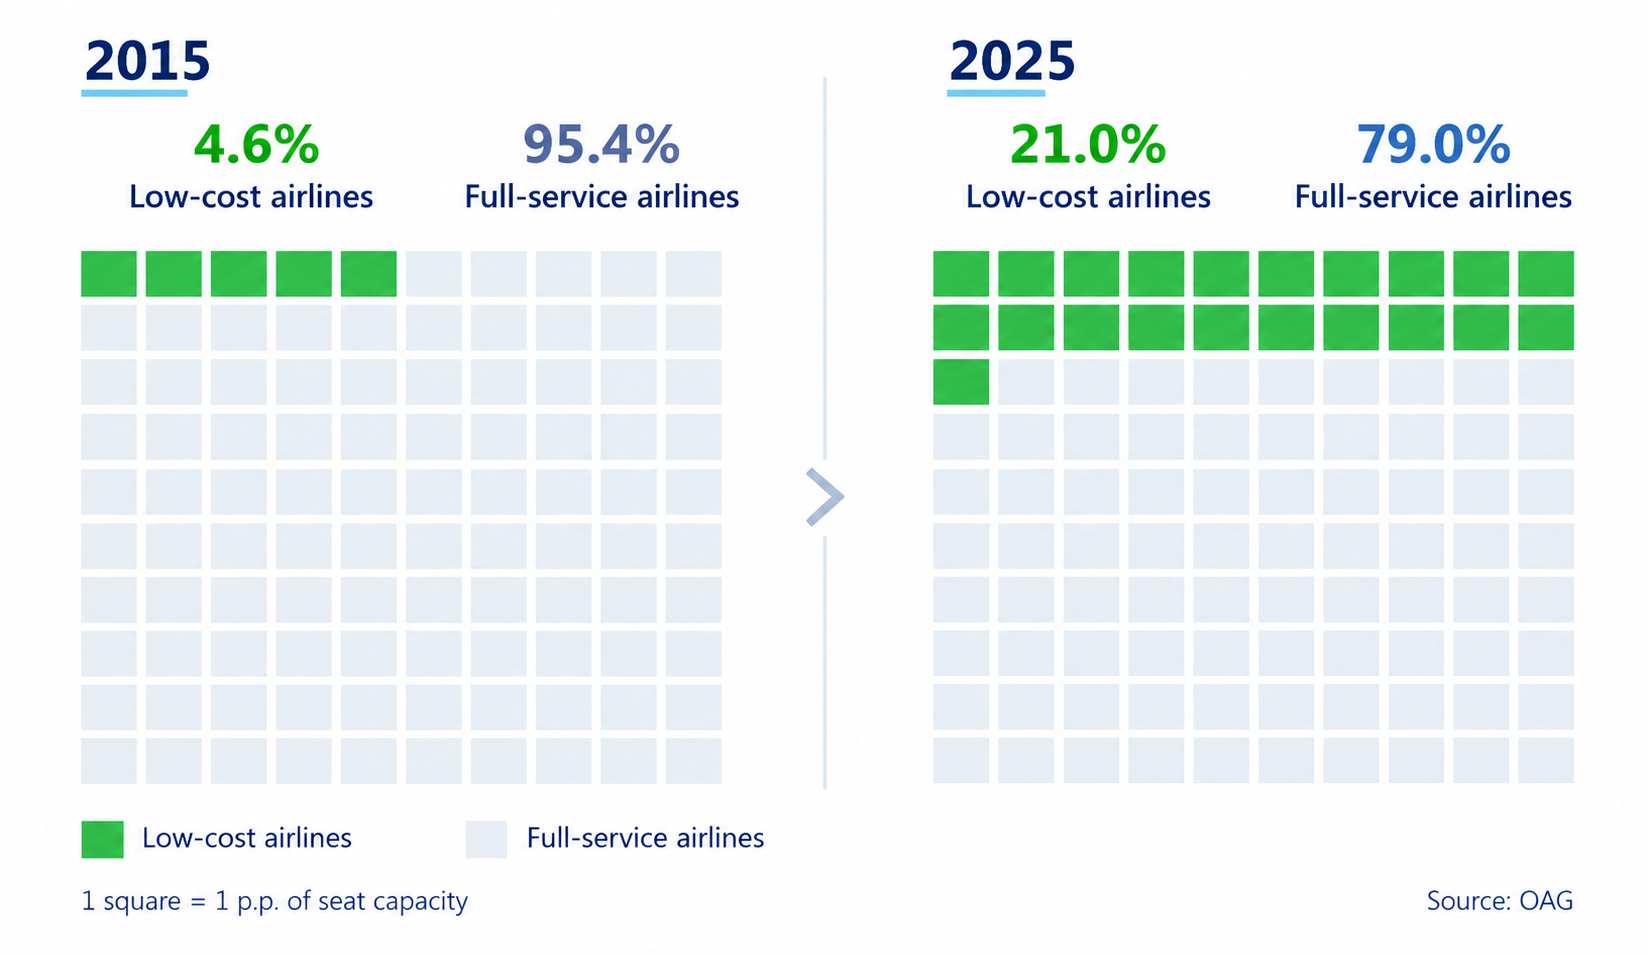
A major driver of market growth is the entry of low-cost carriers (LCC) into the market. Their share of aircraft capacity in Central Asia reached 21% in 2025 (Fig. 5). The largest player is Kazakhstan’s FlyArystan, with a fleet of 28 aircraft.
A boom in low-cost and hybrid airlines also occurred in Uzbekistan. Uzbekistan Airways Express was soon joined by Silk Avia, Centrum Air, and others.
Figure 5. Share of low-cost carriers in total aircraft capacity in 2015 and 2025, %
The fleets and cargo capacities of cargo airlines are growing. The largest of these - My Freighter Airlines from Uzbekistan, which began operations in 2020 - has a fleet of 10 aircraft, including 9 wide-body Boeing 767ERs. In line with the growth of these airlines, the number of passengers served and the volume of cargo handled at Central Asian airports are also increasing (Fig. 6).
Figure 6. Top 5 Airports in Central Asia by number of passengers and of cargo volume handled
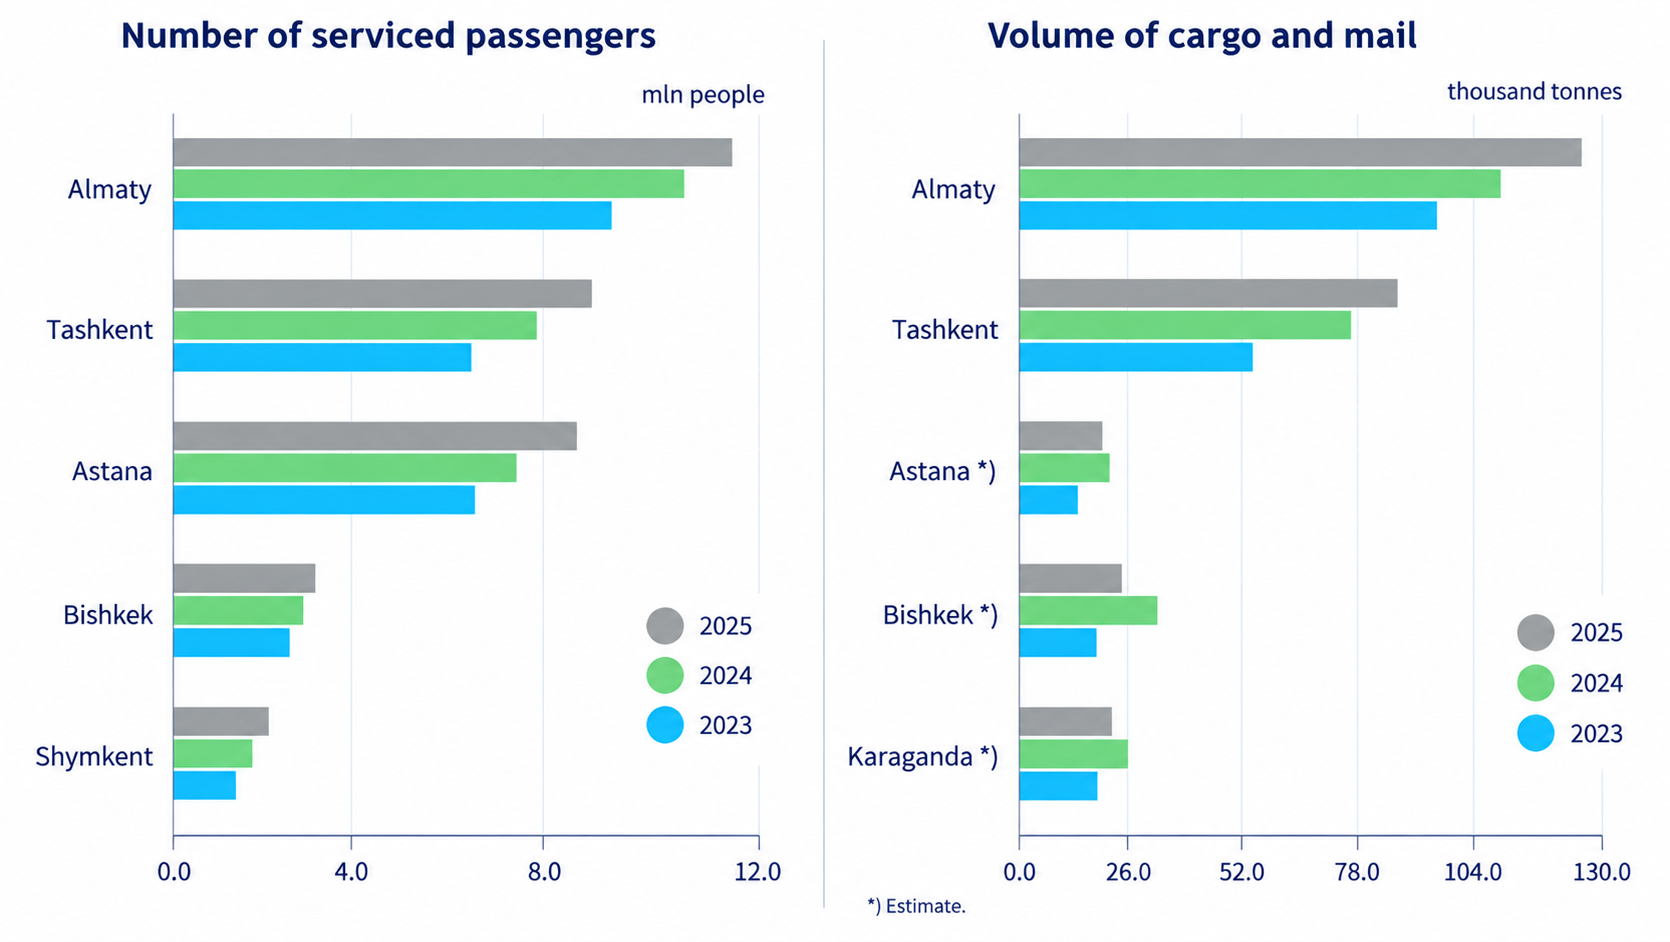
*) Data for 2025 – estimates.
Sources: IATA, airport statistics, calculations and EDB analysts’ calculations.
The growth of the passenger and cargo air transport market is accompanied by the development of airport infrastructure across Central Asia. The new Ashgabat International Airport, built by Turkish companies and meeting ICAO Category IIIB standards, opened in 2016. Infrastructure is also developing rapidly in other countries in the region.
Private investments, including FDI, are being directed toward airport development. The EDB’s Monitoring of Mutual Investments (MMI) database lists several airport development projects in Kazakhstan that have received funding from foreign investors. The FDI stock as of mid-2026 amounts to $1.4 billion. The largest projects are shown in Fig. 7.
Figure 7. FDI stock in the largest air transport infrastructure development projects in Central Asia as of July 1, 2026, in millions of dollars.
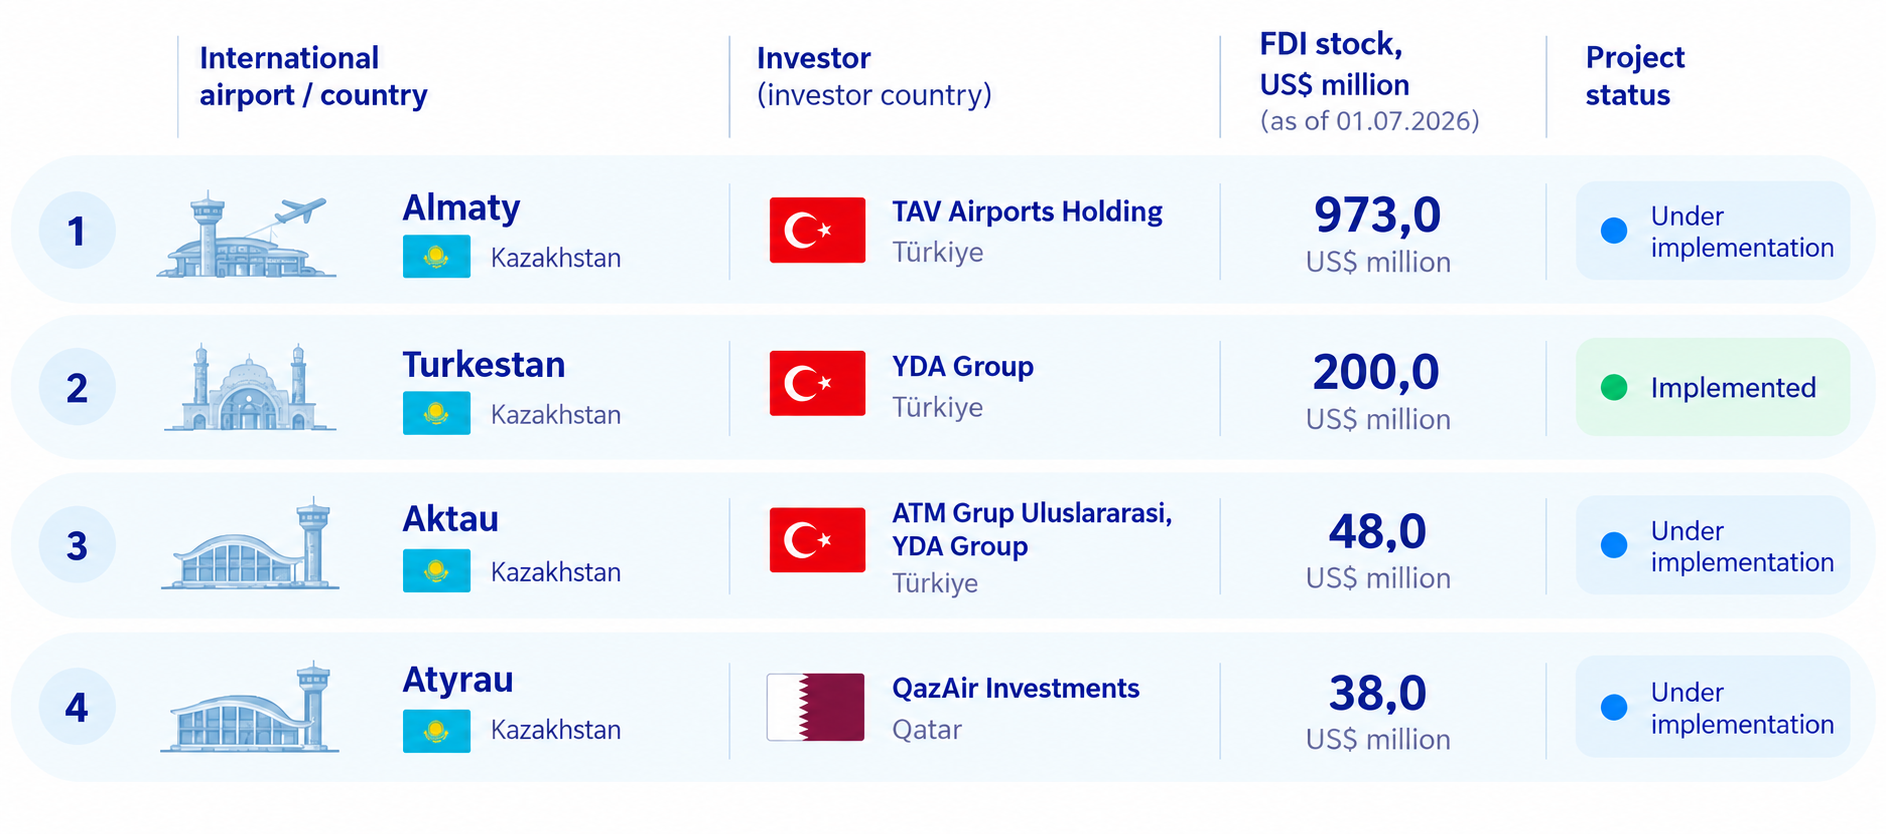
Source: EDB Monitoring of Mutual Investments (MMI).
According to data from the EDB’s Eurasian Transport Network Observatory, 12 major airport development projects with a total investment volume of $5.1 billion are currently underway or planned through 2035 in Central Asia (Figs. 8).
Figure 8. Top 3 airport development projects in Central Asia, in millions of dollars.
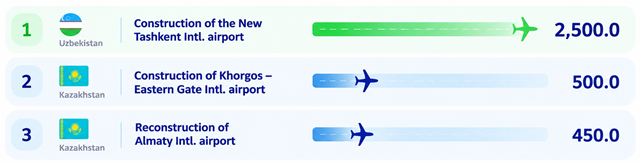
Source: EDB Transport Projects Observatory.
Estimates of investment in airport development in the Kyrgyz Republic range from $190 million, which has already been invested in developing Manas and Jalal-Abad airports according to OJSC 'Airports of Kyrgyzstan', to $770 million, which is an estimate of future investment up to 2035 based on international experience of constructing and modernising regional and international airports.
Infrastructure development goes hand in hand with the growth of the airport management business. There are two national airport groups operating in Central Asia:
-
Uzbekistan Airports—a company established in Uzbekistan with a majority state stake. Shareholdings in the authorized capital are as follows: 10%—Uzbekistan Airways, 7%—Turkish Airlines, and 6%—Maersk Air. The company manages all of the country’s international airports and is responsible for their modernization and infrastructure development. Annual revenue in 2024 is projected to be approximately $550 million.
-
OJSC “Airports of Kyrgyzstan” is a state-owned operator in the Kyrgyz Republic.
-
In Kazakhstan, there are several airport management companies, including those with foreign participation. Almaty Airport is managed by the Turkish TAV Airports Holding; Astana Airport by Terminals Holdings (UAE); Aktau airport by the Turkish ATM Grup, and Uralsk airport by Oral Airport Holding, which includes a stake held by the “Airports of the Regions” (Russian Federation). The airports in Shymkent and Taraz are under the trust management of the SCAT Airlines (Kazakhstan), while Karaganda Airport (Sary-Arka) is managed by the Sky Service private company.
Challenges Facing Civil Aviation in the Region:
-
Weak intra-regional air links: only a limited number of city pairs in Central Asia are connected by air.
-
Limited application of the “open skies” regime in only a few Central Asian countries; market access strictly regulated by intergovernmental bilateral air transport agreements concluded in the 1990s; and the absence of a regional multilateral agreement.
-
The pace of modernization of air transport infrastructure is not keeping up with the growth of passenger and cargo air traffic.
Opportunities for the Development of the Central Asian Aviation Market
|
Area |
What Can Be Developed |
What Could Support Development |
|
Airports infrastructure, Ground Handling |
· Aerodrome infrastructure and equipment, including modernization to improve Aerodrome Operating Minima (AOM) in accordance with ICAO Standards and Recommended Practices (SARPs). · Passenger and air cargo terminals. · Aircraft Maintenance, Repair and Overhaul (MRO) facilities and equipment. · Ground handling infrastructure and services, including facilities for the storage, transportation and blending of aviation fuel. |
Government capital investment, investments by airport operators, private sector entities and development institutions. Modernization of aerodromes, infrastructure and equipment in accordance with ICAO SARPs and international best practice. |
|
Air Cargo and Transit |
· Cargo airlines. · Cargo aircraft fleet. · Air cargo terminals and warehousing facilities. · E-commerce logistics, express delivery infrastructure and related services. |
Leveraging the region strategic location at the crossroads of Europe, Asia and the Middle East. Development of multimodal logistics networks. Liberalization of air cargo services through regional and bilateral air transport agreements in accordance with ICAO SARPs. |
|
Area |
What Can Be Developed |
What Could Support Development |
|
|
|
Modernization of aerodromes to accommodate technical and commercial stops on intercontinental routes connecting Europe, Asia, North America and the Middle East, including their use as alternate aerodromes. Development of Central Asian airports as regional cargo hubs and their integration into international transport corridors. |
|
Passenger Transport and Tourism |
· Passenger terminals and terminal capacity. · Commercial aircraft fleet. · Airline route networks. · Transfer and transit services through Central Asian airports. · LCC segment. · Intra-regional air services and tourism routes, including charter programmes within the framework of the Great Silk Road Tourism Route. |
Enhancement of the civil aviation regulatory framework. Expansion of market access for air carriers, including LCCs. Investment in airlines and aircraft fleets. Development of routes linking cities across the region. Introduction of joint tourism products. Facilitation of airlines membership in global airline alliances and establishment of a regional airline alliance. Development of feeder routes linking regional airports with major hub airports to enhance mobility and regional connectivity. |
|
Intraregional Air Connectivity |
· Infrastructure and equipment at regional airports. · Air links between regional airports of Central Asian countries. · Regional airlines. · Regional aircraft fleet. |
Strengthening the civil aviation regulatory framework and expanding market access for regional airlines. Revision of bilateral air transport agreements to facilitate regional air services. Investment in regional airlines and aircraft fleets. Development of feeder networks and regional air transport connectivity while maintaining the highest levels of flight safety and passenger service quality. |
|
Digitalization |
· Passenger, travel and cargo documentation, including customs documentation. · Flight operations and technical documentation for flight crews and ground personnel. · Customer-facing processes throughout the passenger journey. · Operational and business processes. |
Adoption of international best practices, digital platforms and software solutions developed by IATA and other professional aviation organizations. |
|
Coordination of Industry Development |
· Continuous dialogue between governments, civil aviation authorities and industry stakeholders. |
Establishment of an expert advisory platform involving civil aviation authorities, the private sector, international organizations and multilateral development banks. |
Terms of Use and Disclaimer
The information, conclusions, and recommendations contained in this analytical report are based on data from public, official, and other primary and secondary sources, which are considered reliable as of the date of preparation. However, the Eurasian Development Bank does not guarantee the completeness, accuracy, or timeliness of the information used and assumes no liability for any errors or omissions in the source data.
The opinions, assessments, interpretations, and conclusions presented in this report belong to its authors and do not necessarily reflect the official position of the Eurasian Development Bank. This report is of an informational and analytical nature and does not constitute investment, financial, legal, or any other professional advice.
The full or partial reproduction, citation, reprinting, and distribution of this material—including its publication on external electronic resources — are permitted provided that a reference to the original source is included. When reproducing the material, it is not permitted to alter its content or present individual statements out of context in a manner that could distort their original meaning.
For citation: Omarov, A., & Remezova, N., Zaboev, A., (2026). Central Asia Takes Off: Investments in Aviation Infrastructure. Almaty: Eurasian Development Bank (EDB).
An electronic version of this document is available on the Eurasian Development Bank’s website: https://eabr.org/en/analytics/.
Please send any comments, suggestions, or feedback regarding this document to research@eabr.org.
© Eurasian Development Bank, 2026